
Beneficial-ownership compliance in Mauritius has moved beyond simply recording names in a shareholder register. Organisations must identify the natural persons who ultimately own or control an entity, document how that conclusion was reached, and prepare for expanded reporting requirements taking effect in 2027.
What is the 20% UBO threshold in Mauritius?
The prescribed 20% threshold is a practical starting point for beneficial-ownership analysis. Where a natural person directly or indirectly holds the prescribed percentage, the company should assess and document whether that person falls within the applicable beneficial-owner definition.
The Companies (Beneficial Owner) (Percentage of Shares) Regulations 2019 set the prescribed percentage at 20%, irrespective of the type of share. Financial institutions are subject to a separate significant-interest test referred to in the Regulations.
Did Mauritius introduce the 20% UBO threshold in April 2026?
No. The 20% rule dates back to 2019, when the Regulations were made on 25 October.
What changed on 18 April 2026 was the beneficial-owner definition under the Anti-Money Laundering, Combatting the Financing of Terrorism and Countering Proliferation Financing (Miscellaneous Provisions) Act 2026. The revised definition requires companies to consider direct or indirect ownership at the prescribed percentage, voting rights and, where applicable, other means of ultimate effective control. These may include differential voting rights, the power to appoint senior management, control through debt instruments or positions held within a legal person.
For compliance teams, calculating shareholding percentages is the first step of the review, not the last. A structure may meet the 20% test on paper while control is exercised through debt, voting arrangements or appointment rights.
How do indirect ownership and the Finance Act 2026 affect UBO compliance?
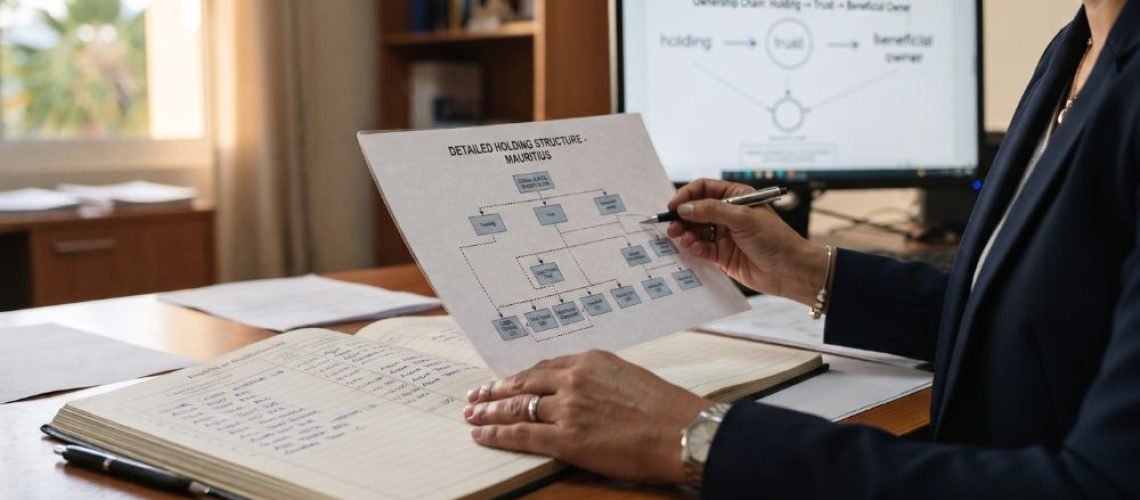
Indirect ownership arises when a natural person holds or controls an interest through one or more intermediary entities. An individual may not appear in the shareholder register of a Mauritius company, yet may have an indirect economic interest or control rights through a holding company, trust, nominee or contractual arrangement.
Companies should map the complete ownership and control chain, calculate indirect interests where relevant, and document voting, appointment and contractual rights that may affect the analysis.
The Finance Act 2026 introduced additional beneficial-ownership reporting requirements. Companies, LLPs and LPs must provide further information on beneficial owners and ultimate beneficial owners, including their date of birth. Existing entities have until 30 June 2027 to submit this additional information.
Why is a shareholder register not the same as a UBO register?
A shareholder register identifies legal titleholders. A UBO analysis traces ownership and control to the relevant natural person.
This distinction matters where the legal shareholder is a holding company, nominee, trustee, partnership or foreign vehicle. The 2026 amendments reinforce that ownership is not measured by shares alone: voting rights and other control mechanisms may also be relevant.
Which changes should trigger a UBO review?
Treat the following as standing review triggers, not one-off checks:
- Share transfers, issues or restructurings
- A new intermediary holding company
- Changes to voting rights or shareholders’ agreements
- New debt arrangements affecting control
- Mergers, redomiciliations or changes in legal form
- A change of trustee, protector, settlor or beneficiary
- Death or change in status of an existing UBO
Each event should also prompt a review of the AML risk profile, CDD file and sanctions screening, not merely an update to the corporate register.
Which Mauritius entities must act before the 2027 UBO deadlines?
Existing companies, LLPs and LPs have until 30 June 2027 to submit the additional BO/UBO information. Existing partnerships have until 31 March 2027 to comply with their new beneficial-owner register requirements.
Obligations vary according to legal form, incorporation date and applicable transitional provisions. GBL entities, funds, trusts and cross-border groups should therefore confirm the precise requirements applicable to their own structure.
How can an UBO register and filing readiness review reduce compliance risk?
An UBO register and filing readiness review tests whether ownership records are complete, consistent and defensible before a filing deadline or inspection creates pressure. It includes mapping ownership chains, identifying the relevant natural persons, checking evidence and reconciling corporate data against AML/KYC and tax records.
CompFidus supports beneficial-ownership reviews, regulatory classification and filing readiness—helping compliance teams close gaps before they become filing or governance issues.
Request an UBO Register and Filing Readiness Review.
Sources of this article: